



Ferro Alloy Manufacturing Business
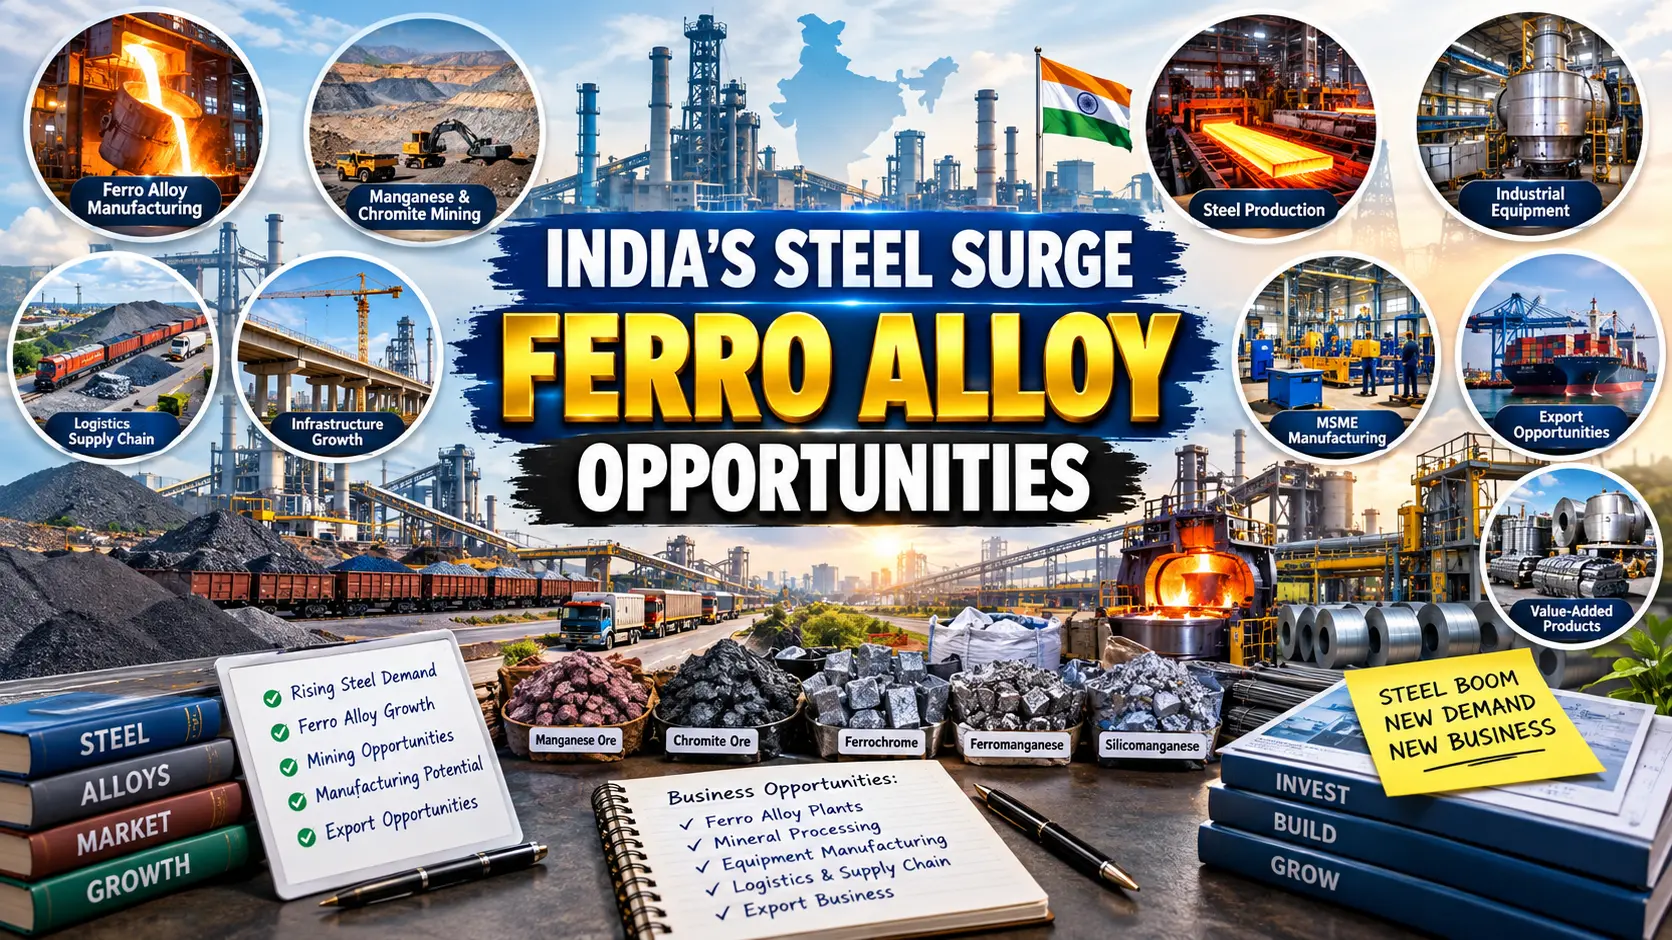
The Indian steel industry is in a path of development which no one could have envisioned ten years ago. The downstream consequences for the allied industry are that huge since the capacity for crude steel has reached a maximum of 200 million tonnes and the national goal is to reach 300 million tonnes by 2030. The ferro alloy industry is at the centre of this opportunity and is a very critical but under-noticed industry that has now come to the fore for entrepreneurs, manufacturers and investors the country over.
Ferrous alloys serve to set the characteristics of a tonne of steel, whether it is strength, hardness, resistance to corrosion or resistance to wear. The demand for various ferro alloys will follow a parallel growth curve with Indian steel mills providing expansion of capacity and upgradation of the product mix, which will meet the requirements of the all theacious sectors like infrastructure, defence, automobiles, and railways. Directly fueled by the steel expansion programme, industry experts believe the Ferro Alloy requirement in India may expand at 7-8% CAGR till FY2030.
Entrepreneurs and MSMEs love this kind of structural demand shift for lasting manufacturing opportunities. The growth is supported by the existing government commitment on strengthening the steel infrastructure, growth in private sector steel production capacity, as well as the government’s continued policy commitment to make India a steel producing country globally, thereby opening up the market for ferro alloy producers, ancillary steel manufacturing companies and service providers in the steel value chain.
What This Development Means for Indian Businesses
Steel production expansion doesn’t happen in isolation in India. It has a trickle-down effect on dozens of allied industries and the Ferro Alloys segment is one of the most direct and meaningful affected ones.
As per the latest estimates, India’s domestic capacity to produce ferro alloy is around 7.5 million tonnes and production is around 6 million tonnes per year. Of that, about 2 million tonnes are being exported and a domestic demand of 3.4 million tonnes by FY2025, up from 2.8 million tonnes in FY2020. Domestic demand for ferro alloy can increase significantly with the increase in steel production up to 300 million tonnes, thereby showing a real demand gap and opening up a real manufacturing opportunity.
There is a definite need for the steel mills to have a steady supply of products like Ferromanganese, Silico manganese, Ferrochrome, Ferrosilicon, Ferrovanadium and various noble alloys, which are quality assured. The movements towards value added, specialty steel grades, often needed for applications in the defence, aerospace, automotive and electrical sectors, are driving increased demand for higher purity, more precisely specified alloy inputs. Entrepreneurs who are able to consistently provide quality and cost competitive inputs on a long-term basis will be able to develop long-term supply relationships with large steel manufacturers.
In addition to primary producers, the development of the sector brings new businesses such as raw material processors, quality testing and refining, and logistics, which are vital to the steel industry and are the types of companies that established steel companies are keen to source domestically.
Why This Industry Could See Stronger Growth
There are several interlocking pillars behind the structural case of the growth of ferro alloy in India, all of which are strong and independent and reinforce each other.
There is a steady demand for structural steel, railway grade steel, automotive flat products etc. which are also the inputs into the ferro alloy production process for government infrastructure spending under PM Gati Shakti, National Infrastructure Pipeline, Bharatmala and dedicated freight corridors.
Though India’s steel consumption kept on rising, it is still far behind the consumption level of the western countries and is pointing towards the future demand. The demand for steel will be rising steadily in the decade as urbanisation and manufacturing activity is gaining momentum under Make in India and PLI schemes across real estate, appliances and capital goods.
The domestic ferro alloy industry has proven its ability to grow which saw the industry capacity grow from 4.3 million tonnes during FY2020 to around 8 million tonnes by March 2025, and has shown great confidence from investors in the industry. Access to competitive power tariffs and large manganese or chrome ore deposits remains a key factor in the addition of new capacity in regions.
India is also the largest exporter of manganese alloys and 3rd largest exporter of Ferrochrome in the world. India’s raw materials competitiveness and manufacturing scale create an export opportunity for the long term, but trade tensions and the EU’s Carbon Border Adjustment Mechanism provide near-term headwinds.
Government Policies and Incentives
There are various industrial investment policies implemented by the Government of India to encourage investment in ferro alloy and allied industries by entrepreneurs.
The National Steel Policy 2017, which can be accessed on the website of the Ministry of Steel, is the key policy document of the Government of India for the steel and the ferro alloy industry. It aims to achieve the 300 million tonne capacity target by 2030-31 and specifically stipulates that the demand for high-grade special steels and alloys should be completely satisfied from local sources, directly establishing the demand environment for ferro alloy producers in the coming years. The policy also looks at raw material security for manganese ore, chrome ore and other ferro alloy inputs.
The Ministry of Steel’s functions as detailed in the Ministry’s About page clearly include the coordination and planning of Alloy Steel & Ferro Alloy Industries, formulation of policies regarding production, pricing, distribution, import and export of ferro alloys, and development of input industries of manganese ore, chrome ore and refractories. This Ministry is directly engaged by entrepreneurs in the ferro alloy industry for promoting the policies, tariff on power and ore related issues.
The first official step for ferro alloy processing and ancillary activities of small and medium scale is registration on the official online registration system of the Ministry of MSME, Udyam Registration Portal, which is a zero-cost online registration system. Collateral-free credit, priority sector lending, technology upgradation subsidies, and government procurement preference are all direct benefits of a valid Udyam Registration Number, applicable to Ferro Alloy & Metallurgical manufacturing businesses.
The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) — jointly set up by the Ministry of MSME and SIDBI — operates the Credit Guarantee Scheme that enables collateral-free lending to micro and small manufacturing enterprises. The guarantee ceiling was raised to Rs 5 crore in April 2023, making it practically relevant for entrepreneurs setting up small ferro alloy processing, slag recovery, or alloy testing units who lack fixed assets to offer as loan collateral.
The PLI Scheme for Specialty Steel — administered by the Ministry of Steel — is the most consequential government scheme for ferro alloy manufacturers. It incentivises production of alloy steel products, high-strength and wear-resistant steel, and specialty rails across three rounds with total investment commitments exceeding Rs 43,000 crore. Every tonne of specialty steel produced under the PLI scheme requires precise ferro alloy inputs — creating a large, policy-guaranteed, growing offtake market for ferromanganese, ferrochrome, ferrovanadium, and other alloys over the scheme period.
Manufacturing startups in the ferro alloy or specialty alloy processing space should explore DPIIT recognition under the Startup India scheme. The scheme’s benefits page details income tax exemption under Section 80IAC for three consecutive years, exemption from prior experience or turnover criteria for government manufacturing tenders, EMD exemption for government bids, and fast-tracked patent examination — making DPIIT recognition particularly valuable for startups entering specialised alloy processing or quality testing services where government procurement can be an early revenue source.
Export-oriented ferro alloy manufacturers can significantly reduce raw material import costs through the Advance Authorisation Scheme on the DGFT portal. This scheme allows duty-free import of inputs — including ore, coke, fuel, and catalysts — that are physically incorporated in or consumed during the production of an exported product. For ferro alloy exporters selling to Japan, South Korea, Europe, or North America, duty-free ore or reductant imports under this scheme materially improve cost competitiveness compared to fully duty-paid landed costs.
Investors and project promoters evaluating ferro alloy manufacturing opportunities can access sector intelligence and active investment project listings through the India Investment Grid — Steel Manufacturing platform. This official government portal lists live investment projects in India’s steel and allied manufacturing sector, provides PLI Specialty Steel scheme details, and offers state-level facilitation information — serving as a single-window reference for identifying co-investment opportunities and project facilitation contacts.
For entrepreneurs planning to establish ferro alloy or chrome alloy units in Odisha — India’s most important ferro alloy-producing state — the Odisha Industrial Infrastructure Development Corporation (IDCO) is the nodal agency for industrial land, estate development, and project facilitation. IDCO’s Land Bank Scheme provides pre-identified plots in established industrial complexes near ore belts in Jajpur, Sundergarh, and Keonjhar, with single-window clearance for land alienation, forest clearance coordination, and R&R facilitation — significantly reducing project development timelines for new ferro alloy units.
Manufacturing Business Opportunities Emerging From This Development
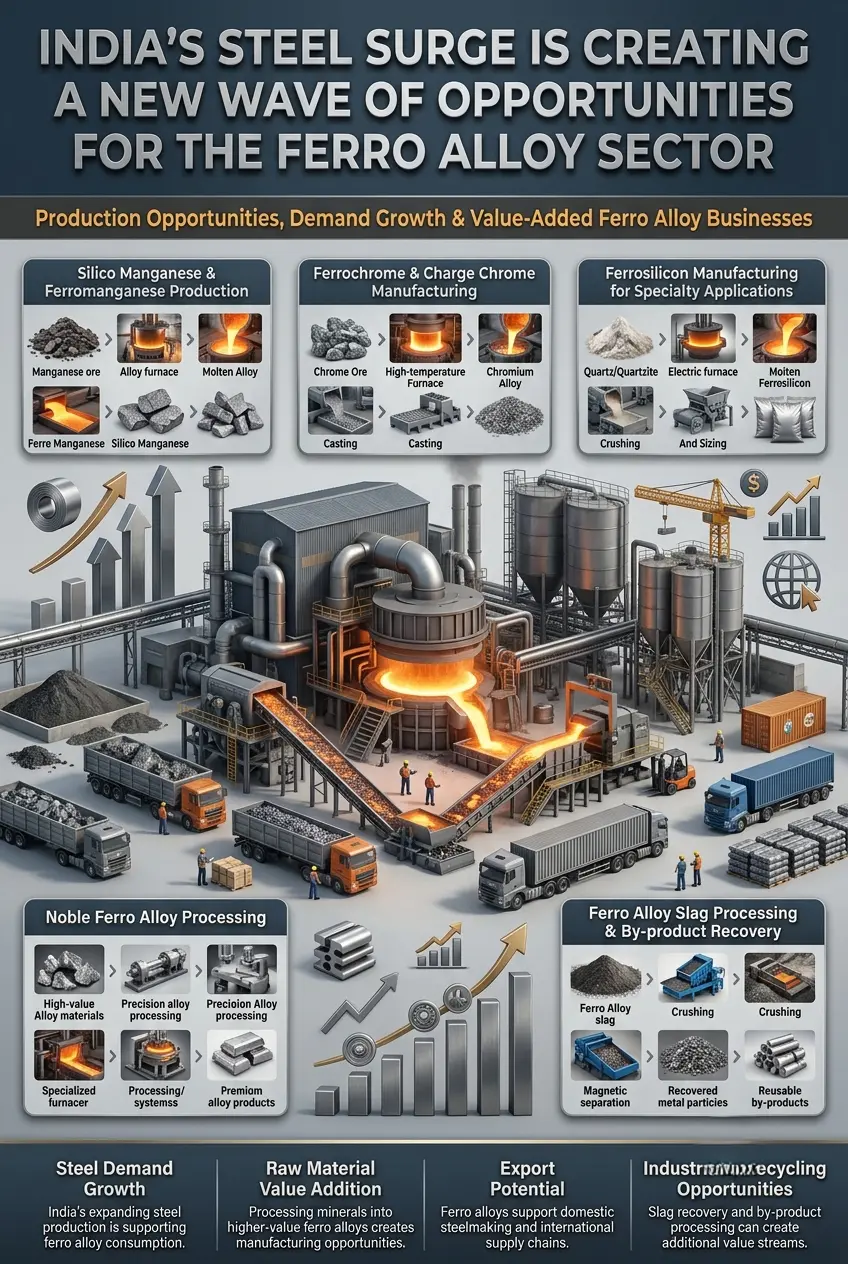
Silico Manganese and Ferromanganese Production
The most commonly used ferro alloys are Silico manganese and Ferromanganese for the deoxidiser and strengthener in carbon and alloy steels. Domestic steelmaking is increasing, and substitution of imported steel in high-purity alloys has become a policy priority, creating a clear expanding market for those who can manufacture the alloys to close tolerances. The units can be set up in the state where there is availability of manganese ore like Odisha, Madhya Pradesh and Maharashtra, both for domestic steel makers and export to East Asia and Europe. For well-capitalised MSME promoters, the small to medium scale operations using EAF are technically and financially viable.
Ferrochrome and Charge Chrome Manufacturing
India is the third largest global producer of ferrochrome, which is mostly used in stainless steel manufacturing. The demand increases in a linear fashion because the demand of stainless steel is growing in the various sectors of domestic market such as kitchen utensils, pharmaceuticals, food processing industries, construction and so on. The natural production area is Odisha, which is endowed with huge reserves of chromite ore. There are two types of ferrochrome, high carbon and low carbon, both of which can be used by entrepreneurs, the latter being premium-priced for speciality applications. As long as quality producers are able to provide regular production, export markets are still available in Japan, South Korea and EU countries.
Ferrosilicon Manufacturing for Specialty Applications
Ferrosilicon is used as a deoxidiser in steel production and is used to improve the strength, elasticity and hardness of structural steels and spring steels. The pressure on domestic production of ferrosilicon has been on the rise, and India is becoming more dependent on imports, as was evident in the case of ferrosilicon. This approach allows for companies to competitively compete in the domestic steel and foundry market if the units are based on quartz reduction or coke reduction processes and have access to an internal power grid.
Noble Ferro Alloy Processing
Specialty steels such as those for defence, aerospace, tool steel and high-performance automotive applications make use of noble ferro alloys (ferrovanadium, ferromolybdenum, ferrotitanium and ferroboron). Due to the expansion of domestic defence production and the growth of the aerospace industry under the Atmanirbhar Bharat, demand is increasing. The unit realisations of these products are much higher than ferro alloys produced in bulk, which makes them a useful niche for technically competent promoters who have the ability to supply the mineral precursors.
Ferro Alloy Slag Processing and By-product Recovery
Metals that can be recovered from slags produced in ferro alloy smelting can be processed into granulated slags, which can be used in soil improvement, road construction, and as a component in cement production. There are a number of known ferro alloy manufacturing units with a huge amount of slag being produced, but not processed downstream, which leaves an asset-light opportunity for smaller plants located in the vicinity of the big plants.
Import-Export and International Market Opportunity
Export Opportunity
India has a number of competitive advantages in the field of ferro alloy exports, such as being able to get domestic ore, having a smelting capacity and a skilled industrial workforce, making them a serious player on the international market in the coming years. Major export markets are Japan, South Korea, Netherlands, Germany, Italy and the USA. The volume of manganese alloys and ferrochrome is the largest, and these are the most important exports. India is the largest exporter of manganese alloys and third largest contributor of ferrochrome in the world.
In the near future, the global trade barriers, anti-dumping safeguards in important markets, the EU Carbon Border Adjustment Mechanism (CBAM) will force ferro alloy exporters to document and lower their carbon intensity. It is important that new entrepreneurs in the sector think green from the beginning as this will be a competitive edge for them in export markets in the near future.
Import Substitution
High purity specialty ferro alloy grades such as low carbon ferrochrome, refined ferrosilicon materials and some noble alloys are being imported in considerable volume on account of some gaps in quality in the domestic grades. International standards-fulfilling manufacturers have an unambiguous import substitution market. Domestic steel producers strongly prefer local supply with quality assurance, due to the supply chain resilience benefit and foreign exchange exposure elimination.
Indian MSMEs and Startups in Related Industries
Indian Metals and Ferro Alloys Limited (IMFA)
Headquartered in Bhubaneswar, Odisha, IMFA is one of the prominent integrated ferrochrome producers having chrome ore mines and power generation facilities in India. The model integrated from ore to finished ferrochrome has proven the viability and scalability of the ferrochrome industry in the mineral belt of Odisha. For entrepreneurs, IMFA is a good example of the need for raw material security and power cost management to ensure their competitiveness, in the longer term.
Ferro Alloys Corporation Limited (FACOR)
FACOR- established in the year 1956, is one of the earliest Ferro alloy manufacturers in India with plants spread in Andhra Pradesh and Maharashtra. The multi-decade operational history of the industry in the production of ferromanganese and ferrochrome provides valuable lessons for new players in this industry about capacity planning and product diversification as well as the technological maturity of the industry and the long-term nature of the business relationship with the domestic steel mills.
Tata Steel’s Ferro Alloys and Minerals Division
Tata Steel’s ferro alloys plant at Saline, Odisha, is the source of ferrochrome and allied products for Tata Steel and the market. The company has stated plans to raise the proportion of value added ferro alloy products to 70-80 percent of production or production, which will provide opportunities for MSMEs in the downstream of the specialty alloy supply chain in the fields of scrap beneficiation, alloy quality testing and ancillary processing.
What Entrepreneurs Should Evaluate Before Investing
Market Demand: Ensure offtake from a specific steel mill/foundry before commissioning capacity. The market for ferro alloy buyers is dominated by the buyers, and it is therefore imperative to have pre-established supply agreements, which are necessary for financial planning.
Raw Material Access: Manganese ore from Odisha, Madhya Pradesh or Goa, and chromite ore close to the area in Odisha. Thoroughly assess ore quality, quantity and logistics before choosing a location.
Power Cost: In EAF operation electricity costs 40-50% of manufacturing cost. Evaluate power tariffs in the state, captive power, and renewable energy procurement options prior to committing to a site.
Technology and machinery: Electric arc furnace technology is predominant in the bulk ferro alloy production. Get several quotations from the equipment vendors and demand guarantees that they perform based on power consumption standards and yield ratios.
Regulatory Requirements: Environmental clearance and consent to operate from State Pollution Control Board is required. Design compliance infrastructure into the project in the planning phase.
Working Capital: High workloads associated with raw material inventory and production process. Provide enough forward space and buffer to take care of commodity prices fluctuations in output markets of ore, coke and ferro alloy.
Quality Standards: buying and selling parties set very strict requirements for composition of goods. From the beginning invest in in-house testing or tie up with accredited lab.
Break-even and Scalability: Smaller units with 6–10 MVA furnace capacity can be commercially viable at appropriate power tariffs. A staged capacity expansion plan is feasible as market relationships are established.
How NPCS Can Help Entrepreneurs Evaluate the Opportunity
NPCS – Niir Project Consultancy Services is a leading industrial consultancy firm with decades of experience supporting entrepreneurs, investors, and institutions across India’s manufacturing sector. For entrepreneurs considering entry into the ferro alloy or allied manufacturing space, NPCS provides end-to-end support — from initial market assessment and technology identification through to Detailed Project Report preparation, plant and machinery evaluation, and financial modelling.
NPCS’s work in the metals and metallurgical sector includes feasibility studies for ferro alloy units, market research covering demand projections and competitive landscape, and technology consultancy covering furnace specifications, raw material sourcing, and environmental compliance requirements. Its project reports are widely used by banks, financial institutions, and MSME development bodies as credible reference documents for credit appraisal.
NPCS has published a comprehensive printed reference book on this subject, covering technology, market analysis, investment parameters, and manufacturing processes in depth. You can access the printed book here: Explore the Complete Book on Ferroalloys.
For a detailed techno-economic Project Report on setting up a manufacturing business in this sector — including plant economics, machinery lists, financial projections, and applicable government incentives — NPCS Project Report here: Explore the Complete Ferro Alloys Manufacturing Guide.
Business Opportunity Snapshot
| Parameter | Details |
| Industry | Ferro Alloys Manufacturing & Allied Processing |
| Market Driver | India’s steel capacity expansion to 300 MT by 2030; ferro alloy demand growing 7–8% CAGR |
| Key Development | Surging steel capex creating sustained demand for ferromanganese, ferrochrome, ferrosilicon, and noble alloys |
| MSME Opportunity | High — small and mid-scale EAF-based units viable; specialty processing and ancillary services also accessible |
| Manufacturing Potential | Strong — existing capacity under-serves projected demand; import-substitution gap in specialty grades |
| Export Potential | Moderate to High — world’s top manganese alloy exporter and third-largest ferrochrome exporter; CBAM adaptation required |
| Import Substitution | High — specialty and noble alloy grades currently import-dependent; domestic production preferred by steel mills |
| Government Support | NSP 2017, PLI Specialty Steel, Udyam MSME Registration, CGTMSE, Startup India, DGFT Advance Authorisation, IDCO Odisha |
| Investment Consideration | Power tariff, ore access, furnace efficiency, working capital, quality certification, environmental compliance |
| Risk Level | Moderate — commodity price volatility, power cost, global trade headwinds; manageable with offtake agreements |
| Growth Outlook | Positive — structurally driven by steel capex; specialty grades growing faster than bulk alloys |
Conclusion
India’s drive toward becoming a 300-million-tonne steel economy by 2030 is creating a once-in-a-generation demand shift for the ferro alloy sector. Domestic ferro alloy consumption growing at 7–8 percent annually, a steel capacity expansion programme backed by firm government commitment and PLI scheme investment of over Rs 43,000 crore, and a clear import-substitution gap in specialty alloy grades — together, these create a genuine and durable manufacturing opportunity for entrepreneurs, MSMEs, manufacturers, and investors.
The opportunity spans multiple product segments — from bulk manganese and chrome alloys to specialty noble alloys for defence and aerospace — and extends across the value chain from primary smelting to ancillary processing, testing, and raw material beneficiation. Mineral-rich states such as Odisha, Andhra Pradesh, Madhya Pradesh, and Jharkhand offer proximity to ore and, in some cases, competitive industrial power.
Entrepreneurs who invest in understanding the market rigorously, securing raw material access, managing power costs strategically, and building quality-assured production systems are well-positioned to build commercially viable ferro alloy businesses aligned with India’s most important industrial growth story. The right action now is to conduct thorough market research, commission a credible feasibility study, prepare a Detailed Project Report, and develop a structured investment plan before committing capital.
Your Investment Deserves the Right Opportunity
Every serious investment begins with choosing the right sector and the right business model. With hundreds of industrial opportunities available across India’s manufacturing and clean-energy landscape, making the most informed choice is critical. NIIR’s Startup Selector tool helps entrepreneurs, MSMEs, and investors identify the most suitable business opportunities based on their investment capacity, location, and interests — so your capital is directed toward a venture with the strongest fit and potential.


